There is a wonderful trick in corporate finance: sometimes you don’t make the liability disappear. You simply change where you look for it.
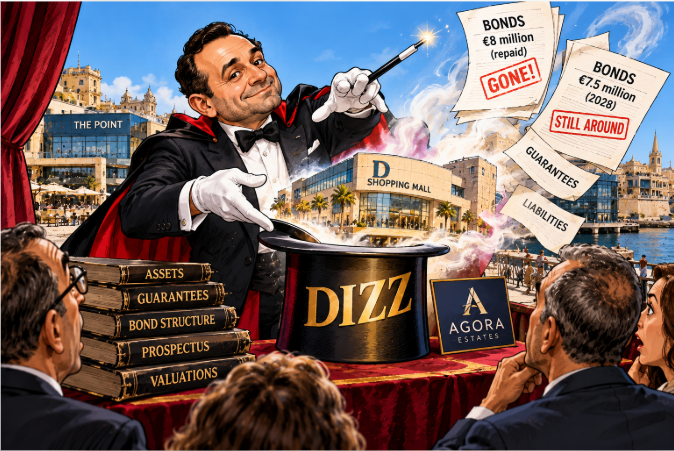
D Shopping Mall has now been sold to Agora Estates, which plans to rebrand the shopping centre. On the face of it, this is a perfectly ordinary property transaction: one owner sells, another buys, and the new owner presumably sees opportunities where the old owner saw an asset to dispose of.
But the interesting story is not the shopping centre.
It is the money behind it.
On 5 October, D Shopping Malls Finance announced that the transaction had been completed and that D Shopping Malls Limited had been transferred to the investor. The consideration received by the Dizz Group was then used to repay the €8 million Dizz Finance bonds that matured in October 2026.
So far, so good.
One liability has genuinely been paid off. But that is not the end of the story.
D Shopping Malls Finance has another €7.5 million of 5.35% unsecured bonds due in 2028. Those bonds were originally guaranteed by D Shopping Malls Limited — the very company which has now changed hands. That meant the bondholders had to be called together to approve a revised guarantee structure.
And this is where things become rather more interesting.
The original support structure included the D Mall lease, the Centerparc lease and the Qui-Si-Sana property. Under the revised structure, D Mall is replaced by D Hub, an office property in Mrieħel independently valued at €17 million, together with the Centerparc lease and the Qui-Si-Sana property. The bondholders approved the proposed changes on 28 September.
Again, there is nothing inherently sinister about this. Companies restructure. Assets are bought and sold. Guarantees change. Debt gets refinanced. Investors approve new security arrangements. That is how finance is supposed to work. But it is also why ordinary investors need to look beyond the headline.
Because an asset is not the same thing as cash.
A property valued at €17 million is not €17 million sitting in a bank account. A guarantee is not the same thing as repayment. A rental income stream is not the same thing as liquidity. And a change in the identity of the asset backing a bond does not make the underlying obligation disappear.
This matters because Malta has developed an unusually deep retail market for corporate bonds. Ordinary savers have become an important source of finance for property companies and other businesses. That is not necessarily a bad thing.
Quite the opposite. A functioning capital market can allow businesses to raise money, invest, develop property and expand without relying exclusively on banks. But with that opportunity comes responsibility – and not just for investors.
Companies issuing bonds have a responsibility to make their financial structures understandable. Advisers and intermediaries have a responsibility to explain risk rather than merely explain yield. Regulators have a responsibility to ensure that investors are given enough information to understand what they are actually buying.
And investors have a responsibility to read the prospectus before being seduced by the interest rate.
There is another interesting development here.
On the same day that the Malta Stock Exchange recorded approval of Agora Estates’ prospectus for up to €20 million of 5.75% secured bonds maturing in 2038, the D Shopping Malls transaction was being completed. Agora says its new bonds will be secured by first-ranking special hypothecs over five properties forming part of its security package.
That is not evidence of anything improper. Nor should it be presented as such.
It is, however, a useful reminder of how sophisticated the machinery behind Malta’s bond market has become.
Property changes hands.
Companies change. Guarantees are substituted. Assets are moved. New bonds are issued. Old bonds are redeemed.
And somewhere in all that financial choreography sits the person who bought €10,000 of a corporate bond because the interest rate looked attractive.
That investor’s question should always be very simple:
What exactly is securing my money?
Not what is the property worth on paper. Not what the company says it plans to do. Not how attractive the coupon looks. What happens if things go wrong?
Because financial liability doesn’t really disappear. It moves.
And if we are going to encourage ordinary Maltese investors to participate in the capital market, we should make sure they can see where it has moved.
That is how you make financial liability DIZZappear.
Sources
- Malta Stock Exchange — Agora Estates €20m secured bond prospectus approval
- D Shopping Malls Finance — 5 October 2026 transaction update
- D Shopping Malls Finance — 28 September 2026 bondholders’ meeting outcome
- D Shopping Malls Finance — Bondholders’ meeting and revised guarantee structure
- Agora Estates — Investor Relations and financial information
- The Business Picture — Agora Estates buys D Shopping Mall next to The Point, rebrand planned